Nobody wants to move twice in a downsize
The median house in Massapequa sold for $765,000 and took about 27 days to go under contract, then another 45 to 60 days waiting on the buyer's mortgage. That is 72 to 87 days in total, for a house that was ready to show on day one. Now add the part specific to downsizing and retiring: you cannot commit to the next place until you know what this one brings, and you cannot be certain what this one brings until it is under contract with a buyer whose financing has cleared.
That uncertainty is the real cost of the retail route for a downsizer. A written cash number collapses it into a fact you can plan around, whether or not you sell to us.
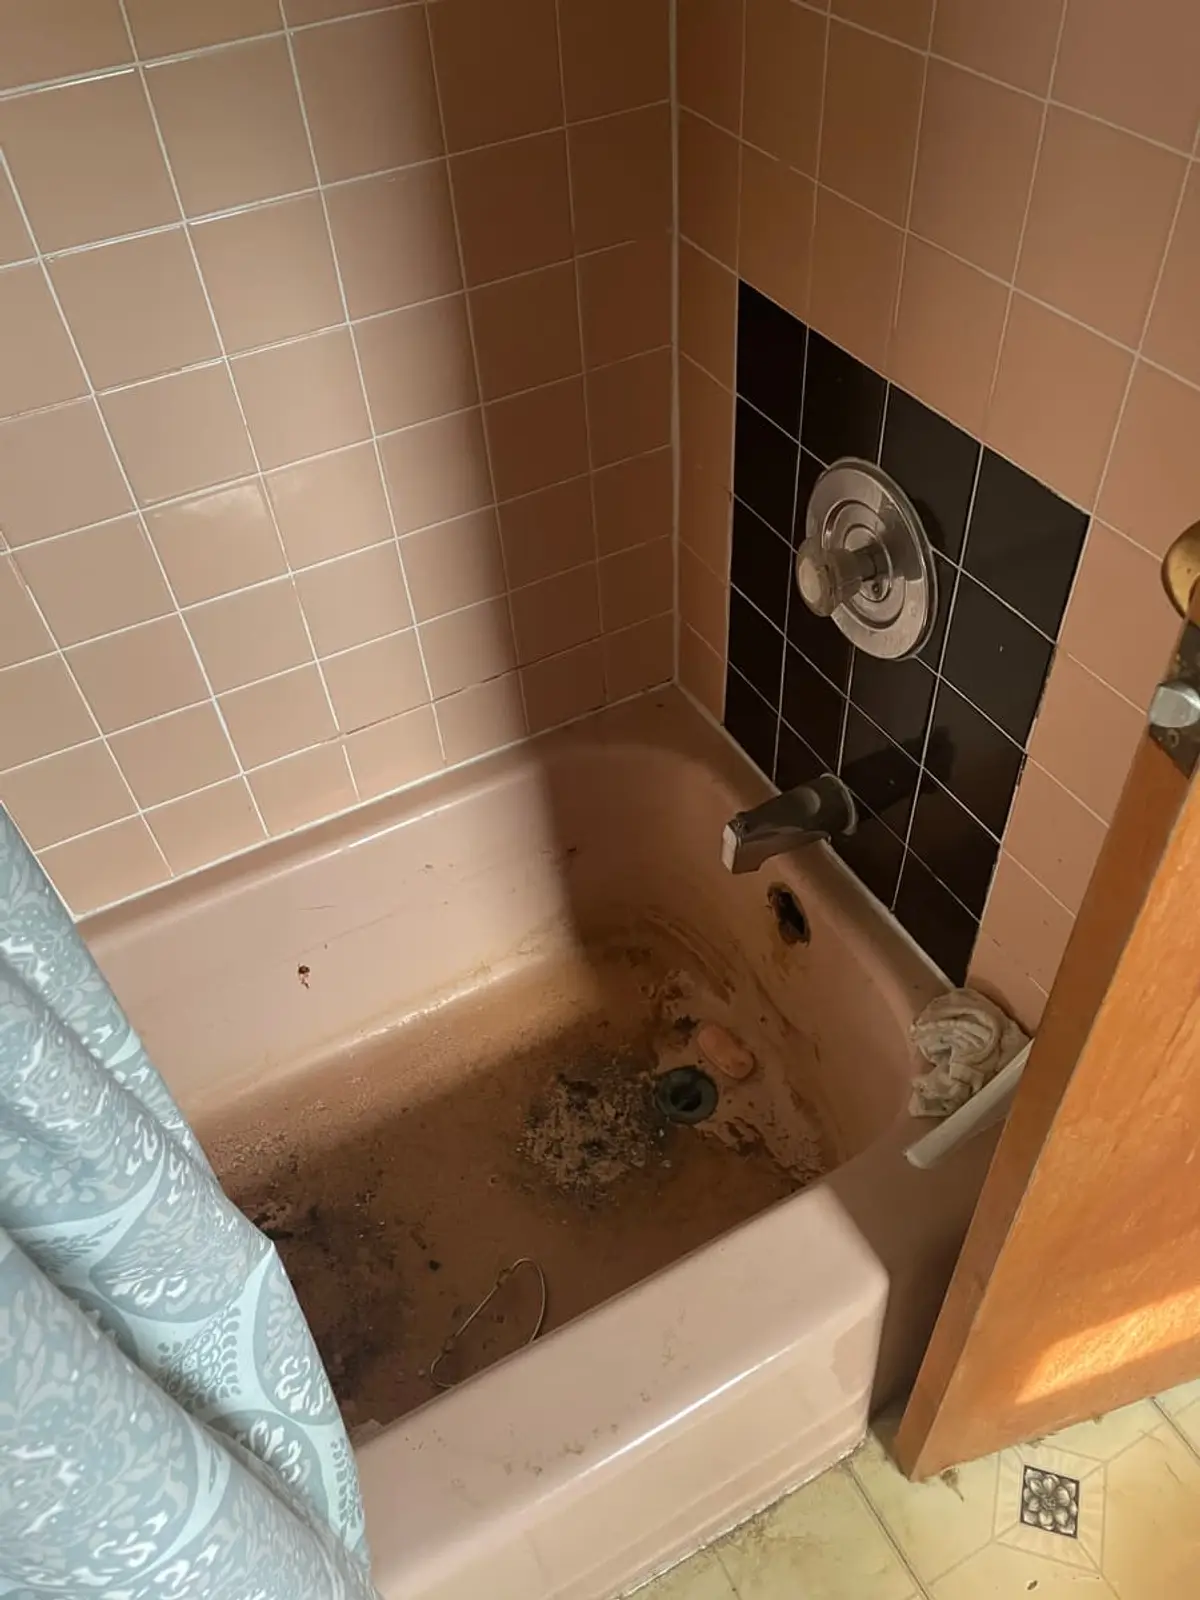
Clearing a Massapequa house before you downsize
The sorting is genuinely hard and it is worth saying so. What we can remove is the deadline on it. You are not clearing the house to make it show well for strangers, because there are no showings.
So do it at whatever pace suits you, keep what you want, and let the rest transfer with the house. Plenty of Massapequa families have handled a downsize exactly that way and described the cleanout as the biggest relief in the whole process.
The Massapequa market underneath this
The Massapequa median has barely moved year over year as of 2026-05, at 0.16%. Flat is the hardest market to price a fixer into, because there is no upward drift to cover a mistake and no urgency pushing buyers to overlook a problem. A $765,000 median puts Massapequa in the band where buyers are stretching to afford the house and have nothing left for the roof. That is precisely the buyer who walks away from a property needing work, and it is why condition matters more here than the price alone suggests. The median house here goes under contract in about 27 days, which is quick for Long Island. It is also a figure that only applies to property in showable condition.
A house on Roosevelt Avenue. In Massapequa, bought and paid for by us.
The repairs a downsizer does not have to make
The mechanicals are what matter on a Massapequa house of that age: the boiler, the electrical service, the roof. Those are the items a buyer's lender will flag, and they are expensive exactly when you are retiring and least want a large bill.
We are pricing all of it anyway, because we do this work every week at contractor rates. The same repairs cost us in the region of half what you would be quoted, which is why we can take on a house that a retail buyer's bank would decline.
How we arrive at a number on a home you are downsizing from
For a home you are downsizing from, the starting point is the price once it is fully repaired. We subtract what the repairs cost and then a margin for being wrong about the price or the repairs. No algorithm and no trade secret: that is how the number is built.
- What it is worth repaired. Not the Massapequa median of $765,000 on its own, but what houses like yours on your street actually closed at recently.
- What the work costs. Roof, boiler, electric, the kitchen and bath. In Massapequa the stock is largely cape cod and hi-ranch, and on houses that age the mechanicals are usually the expensive part rather than the cosmetics.
- How long we will hold it. The median Massapequa house goes under contract in about 27 days once it is showable, then waits 45 to 60 days more on the buyer's lender. Ours has to get to showable first, and we carry taxes and insurance across the whole of it.
- What we are wrong about. Every renovation turns up something nobody could see on the walk-through. We build that risk into the price, and it explains a good part of why cash offers come in below retail.
Where our margin actually comes from
Plainly, because buyers are often vague here: we run millions of dollars of construction a year. At that volume we pay contractor prices for materials and keep steady crews working twelve months a year, so a given renovation costs us roughly half of what a homeowner pays for the same job.
That is where our margin is. It is also why fixing the house up yourself first rarely pays off. You would be paying retail for the work and counting on the sale price to cover it, and it usually does not. We earn our money on the construction side, not on the price we pay you.
If the figure does not work, say so; we would rather know than try to talk you round. We will look at what is going on and tell you honestly which options make sense, including the ones without us. Listing with an agent is the better route for plenty of sellers, and we will tell you if it is yours.
Talk to a CPA before you downsize, not after
A house bought decades ago and held through every Long Island boom since can carry a large gain. There is a primary-residence exclusion, there are rules about how long you lived there, and there are consequences to getting the timing wrong.
Downsizing tax is a CPA's job and it is worth the appointment. Ask specifically about the exclusion and about your cost basis including the improvements you have made over the years, because people routinely forget decades of receipts that would reduce the bill.
How selling a home you are downsizing from in Massapequa works
- 1
Start with the basics
Where the house is (11758) and a rough sense of its condition is all we need to begin. Call or use the form. Nothing needs fixing or clearing out beforehand.
- 2
We come and look at it
One visit, one person, usually under half an hour. On a cape cod or hi-ranch of the age most of Massapequa was built, we are mainly looking at the roof, the boiler and the electric rather than the kitchen.
- 3
A written offer within 24 hours
One figure, in writing, inside 24 hours. Not a range. Show it to a Nassau County agent if you want a second view; if the house is already in good enough shape to list, an agent may get you more, and we will say so.
- 4
Closing happens on your date
If you need it done quickly, it can be. If probate, a tenant or a move means waiting, we wait. What you skip is the 72 to 87 days a Massapequa listing usually spends on finding a buyer and then on that buyer's lender.
Taking your time over a Massapequa downsize
Nobody is going to chase you about downsizing. Take the number, sit with it, talk to your family, and call in three months or not at all. That is a completely normal outcome of these conversations and it is fine.
What we would suggest is getting the figure early rather than late, because it makes every other decision concrete. Where you can afford to move, whether you sell before you buy, what the CPA is actually working with.
Common questions
Can I stay in the Massapequa house until the place I am downsizing to is ready?
That is one of the more common requests and it is generally workable. The date is a term of the contract, so it is negotiated rather than dictated by somebody's lender.
Do we have to clear the house before we downsize?
No. Take what you want and leave the rest. The clearing is ours after closing and it does not move the number.
Will we pay capital gains tax when we downsize?
That is a CPA question and it depends on your gain, the primary-residence exclusion, and your cost basis including decades of improvements. Ask before you sign a contract, not after. It is the most valuable hour in this whole process.
Would a retiring owner get more listing it with an agent?
On a well-kept Massapequa house with no deadline, quite possibly, and we will tell you if we think so. Our number makes more sense when the house needs work you do not want to fund, or when the timing of the next place makes a months-long sale impractical.